Atal Pension Yojana 2026: Chart, Eligibility, Status and Statement

The Atal Pension Yojana (APY) is the government’s guaranteed pension scheme for people without a formal pension, such as farm workers, drivers, shopkeepers and gig workers. You join between 18 and 40, pay a small fixed amount from your bank account, and from age 60 you get a pension of Rs 1,000, Rs 2,000, Rs 3,000, Rs 4,000 or Rs 5,000 a month for life.
Gross enrolments stood at 9,29,47,723 on 30 June 2026, of whom about 4.57 crore are women, according to a Lok Sabha answer of 3 August 2026. A record 1.35 crore joined in 2025-26, PIB reported. Below: the full contribution chart, eligibility, how to apply, and how to check your APY status and statement.
What is the Atal Pension Yojana?
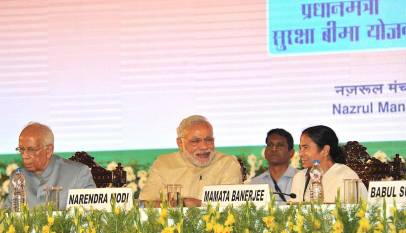
APY is a voluntary, contribution-based pension scheme launched on 9 May 2015 and administered by the Pension Fund Regulatory and Development Authority (PFRDA) on the National Pension System (NPS) platform. The Central Government guarantees the minimum pension you choose.
The PFRDA scheme page describes three benefits, often called the triple benefit:
- Your pension: a guaranteed Rs 1,000 to Rs 5,000 a month from age 60 until death.
- Your spouse’s pension: after your death, your spouse gets the same amount for life.
- Money back to the family: after both of you die, your nominee receives the pension wealth built up until you turned 60.
To get all three, you must keep paying the fixed contribution from the day you join until you turn 60.
Atal Pension Yojana chart: monthly contribution by age
What you pay depends on your joining age and the pension you pick. The table is PFRDA’s indicative monthly contribution chart. The indicative corpus returned to your nominee is Rs 1.7 lakh for the Rs 1,000 pension, Rs 3.4 lakh for Rs 2,000, Rs 5.1 lakh for Rs 3,000, Rs 6.8 lakh for Rs 4,000 and Rs 8.5 lakh for Rs 5,000.
| Joining age | Years of paying | Rs 1,000 pension | Rs 2,000 pension | Rs 3,000 pension | Rs 4,000 pension | Rs 5,000 pension |
|---|---|---|---|---|---|---|
| 18 | 42 | Rs 42 | Rs 84 | Rs 126 | Rs 168 | Rs 210 |
| 19 | 41 | Rs 46 | Rs 92 | Rs 138 | Rs 183 | Rs 228 |
| 20 | 40 | Rs 50 | Rs 100 | Rs 150 | Rs 198 | Rs 248 |
| 21 | 39 | Rs 54 | Rs 108 | Rs 162 | Rs 215 | Rs 269 |
| 22 | 38 | Rs 59 | Rs 117 | Rs 177 | Rs 234 | Rs 292 |
| 23 | 37 | Rs 64 | Rs 127 | Rs 192 | Rs 254 | Rs 318 |
| 24 | 36 | Rs 70 | Rs 139 | Rs 208 | Rs 277 | Rs 346 |
| 25 | 35 | Rs 76 | Rs 151 | Rs 226 | Rs 301 | Rs 376 |
| 26 | 34 | Rs 82 | Rs 164 | Rs 246 | Rs 327 | Rs 409 |
| 27 | 33 | Rs 90 | Rs 178 | Rs 268 | Rs 356 | Rs 446 |
| 28 | 32 | Rs 97 | Rs 194 | Rs 292 | Rs 388 | Rs 485 |
| 29 | 31 | Rs 106 | Rs 212 | Rs 318 | Rs 423 | Rs 529 |
| 30 | 30 | Rs 116 | Rs 231 | Rs 347 | Rs 462 | Rs 577 |
| 31 | 29 | Rs 126 | Rs 252 | Rs 379 | Rs 504 | Rs 630 |
| 32 | 28 | Rs 138 | Rs 276 | Rs 414 | Rs 551 | Rs 689 |
| 33 | 27 | Rs 151 | Rs 302 | Rs 453 | Rs 602 | Rs 752 |
| 34 | 26 | Rs 165 | Rs 330 | Rs 495 | Rs 659 | Rs 824 |
| 35 | 25 | Rs 181 | Rs 362 | Rs 543 | Rs 722 | Rs 902 |
| 36 | 24 | Rs 198 | Rs 396 | Rs 594 | Rs 792 | Rs 990 |
| 37 | 23 | Rs 218 | Rs 436 | Rs 654 | Rs 870 | Rs 1,087 |
| 38 | 22 | Rs 240 | Rs 480 | Rs 720 | Rs 957 | Rs 1,196 |
| 39 | 21 | Rs 264 | Rs 528 | Rs 792 | Rs 1,054 | Rs 1,318 |
| 40 | 20 | Rs 291 | Rs 582 | Rs 873 | Rs 1,164 | Rs 1,454 |
How to use the chart as an APY calculator
Find your age in the first column and read across to the pension you want. That figure is your monthly payment until 60. A 25-year-old who wants Rs 5,000 a month pays Rs 376 a month for 35 years, a total of about Rs 1.58 lakh. A 35-year-old choosing the same pension pays Rs 902 a month for 25 years, or about Rs 2.71 lakh. Joining early costs far less.
The APY FAQs say you can raise or lower your pension slab once a financial year, for a fee of Rs 50.
Atal Pension Yojana eligibility and age limit
Any Indian citizen aged 18 to 40 with a savings account at a bank or post office can join, unless they are or have been an income-tax payer. That bar has applied to new accounts since 1 October 2022.
- Age limit: you can join until your 40th birthday, but not after it.
- Bank account: a savings or post office savings account is compulsory; the contribution is auto-debited from it.
- One account only: one APY account per person; eligible family members can each open their own.
- Nominee: mandatory. If you are married, your spouse is the default nominee.
What if I start paying income tax later?
Nothing changes. You only need to be a non-taxpayer on the day you apply, the FAQs say, and accounts opened by 30 September 2022 continue regardless of tax status.
How to join Atal Pension Yojana
- Offline: submit the APY registration form at the bank or post office branch that holds your savings account, with your pension slab, payment frequency (monthly, quarterly or half-yearly) and nominee. Give Aadhaar and a mobile number for SMS updates.
- Online: use the eAPY registration page run by Protean, the central recordkeeping agency. Details come from Aadhaar and you sign with e-sign, with no paper form. Many banks also offer APY in net banking.
After joining, you get a PRAN (Permanent Retirement Account Number). It is separate from any NPS PRAN you already have.
How to check APY status and download your statement
You can see your APY status and download the statement free on Protean’s APY e-PRAN and statement page, using your PRAN and bank account number.
- Choose “search with PRAN” and enter your PRAN and savings account number. If you do not know your PRAN, search with your name, account number and date of birth instead.
- Under “Views for Subscriber”, pick “APY ePRAN and Master details view” for your account details, or “APY/Swavalamban Statement View” for the statement.
- Select the financial year, enter the captcha and submit, then save the page as a PDF.
The “APY and NPS Lite” mobile app also shows your balance, last five contributions and e-PRAN after a PRAN and OTP login.
What happens if you miss an APY payment?
You pay overdue interest of Re 1 for every Rs 100 of delayed contribution per month, and it is added to your own pension corpus. The account is not closed for non-payment.
But maintenance charges keep being deducted until the balance runs out, so clear missed amounts with interest as soon as you can.
Atal Pension Yojana exit rules
Yes, you can leave before 60, but you lose the guarantee. On voluntary exit you get back only your own contributions plus the income earned on them, minus charges.
| Situation | What happens |
|---|---|
| You reach 60 | Apply at your bank for the monthly pension, paid for life |
| You die after 60 | Your spouse gets the same pension for life; the nominee then gets the corpus |
| You die before 60 | Your spouse can keep paying until the date you would have turned 60 and then draw the pension, or take the corpus in one go |
| Voluntary exit before 60 | Refund of your contributions and their earnings, less charges |
For anyone who joined before 31 March 2016 and received the old government co-contribution, that co-contribution and its earnings are not refunded on early exit.
Is Atal Pension Yojana worth it?
For a worker with no employer pension, APY offers a guaranteed income for life, for you and then your spouse. The catch: the pension is fixed in rupees, so Rs 5,000 in 30 years will buy far less than today. Treat it as a base layer, not your whole plan.
Pair it with tax-free savings such as the Public Provident Fund. If you also need a regular payout sooner, the Post Office Monthly Income Scheme pays interest every month. Informal workers should also get an e-Shram card to find other welfare schemes, and parents can start a child’s pension with NPS Vatsalya.
Frequently asked questions
What is the maximum pension under Atal Pension Yojana?
Rs 5,000 a month, guaranteed by the Central Government, from age 60.
Is there an APY helpline?
Yes. Call PFRDA on 1800-110-069 if you want to join, or Protean CRA on 1800-889-1030 if you already have an account.
Sources: PFRDA, Atal Pension Yojana; PFRDA APY contribution chart; PFRDA APY FAQs; Lok Sabha Unstarred Question 2361, 3 August 2026; PIB, 20 May 2026. Rules can change; check with your bank or PFRDA before you join. This is general information, not financial advice.
Featured image: Prime Minister’s Office / Wikimedia Commons, GODL-India (resized). The launch of Atal Pension Yojana and two insurance schemes at Nazrul Manch, Kolkata, in May 2015.